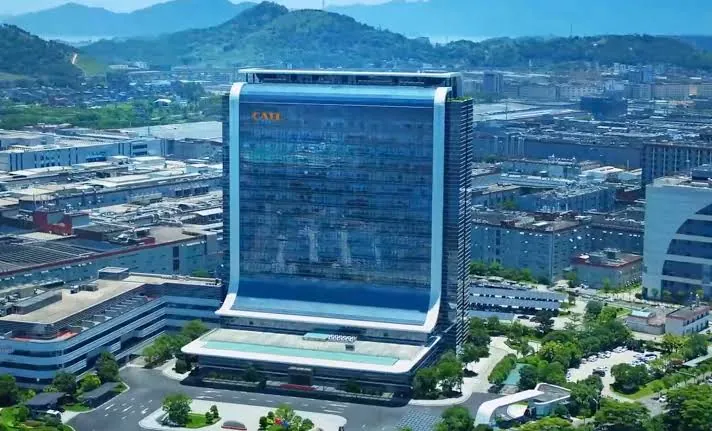
China's battery giant CATL faces existential strategic choices following an epic market sell-off totaling approximately US$130 billion, revealing deep fissures beneath the surface of electric vehicle market dominance. The massive divestment signals profound investor apprehension regarding the sustainability of hyper-growth models amid escalating global economic uncertainty and intensifying technological competition.
As the world's preeminent battery supplier, CATL's valuation is intrinsically tied to the global transition toward electrification. However, the recent market turbulence forces the company to reassess its risk exposure, balance aggressive international expansion with domestic operational pressures, and navigate a landscape where technological superiority is no longer a guaranteed shield against financial volatility.
The scale of the capital withdrawal underscores a systemic shift: the investment thesis supporting unchecked expansion is being challenged by macroeconomic headwinds and the realization that supply chain resilience now demands diversified, often geographically constrained, partnerships.
Market Dynamics and Operational Stress
CATL maintains a dominant position, particularly in the high-volume Lithium Iron Phosphate (LFP) chemistry, which offers cost advantages critical for mass-market EV adoption. Despite this technical stronghold, the recent selling pressure has highlighted the vulnerability of centralized manufacturing giants to sudden shifts in sentiment, irrespective of core product strength. The company's ability to execute flawless logistics and maintain high-volume production remains paramount in mitigating investor fear.
Commercially, CATL is engaged in an intense global race against both domestic Chinese rivals and established Western battery players. Its expansion into European and North American markets, while strategically vital for de-risking geopolitical concentration, requires substantial capital expenditure and complex regulatory compliance, all while facing a backdrop of shrinking profit margins in certain segments.
The company’s immediate challenge is transforming market anxiety into a focused operational advantage. This involves optimizing production efficiency, securing long-term raw material contracts to hedge against commodity price swings, and demonstrating clear pathways to profitability rather than relying solely on volume growth.
Geopolitical Implications and Future Trajectories
The crisis surrounding CATL is not merely a financial correction; it is a microcosm of the broader techno-economic friction between China and the West. Western governments are aggressively implementing subsidy structures and domestic manufacturing mandates, such as the Inflation Reduction Act in the US, designed explicitly to curtail reliance on Chinese supply chains.
This geopolitical pressure forces CATL into a delicate balancing act: maintaining its massive production scale in China while simultaneously building localized, compliant manufacturing footprints abroad. Success in this diversification hinges on the speed and efficacy of its regional partnerships and its ability to meet stringent, non-tariff technical requirements set by importing nations.
Ultimately, the pressure on CATL compels a strategic evolution from being solely a volume powerhouse to becoming a resilient, globally integrated technology partner. Its future valuation will depend less on its current production capacity and more on its demonstrated adaptability to a fragmented, politically charged, and increasingly localized energy landscape.